
GCC expatriates
A period of strong disposable income can be temporary. The assets you build from it can last considerably longer.
A whole financial life, in context.
For expatriates living and working in the UAE, Qatar, Saudi Arabia, Kuwait, Bahrain and Oman who want their earning years to support lasting assets and future choices.
Financial life today
- Monthly surplus after current commitments, including family support abroad.
- Employer benefits and end-of-service arrangements whose terms should be checked.
- Education, property, business or retirement goals with different deadlines.
- A future home country, another destination or a longer stay in the region.
- For example, earnings in AED, QAR or SAR may fund university fees in GBP or EUR, while retirement is planned in another country. Exchange rates can change what those savings buy.
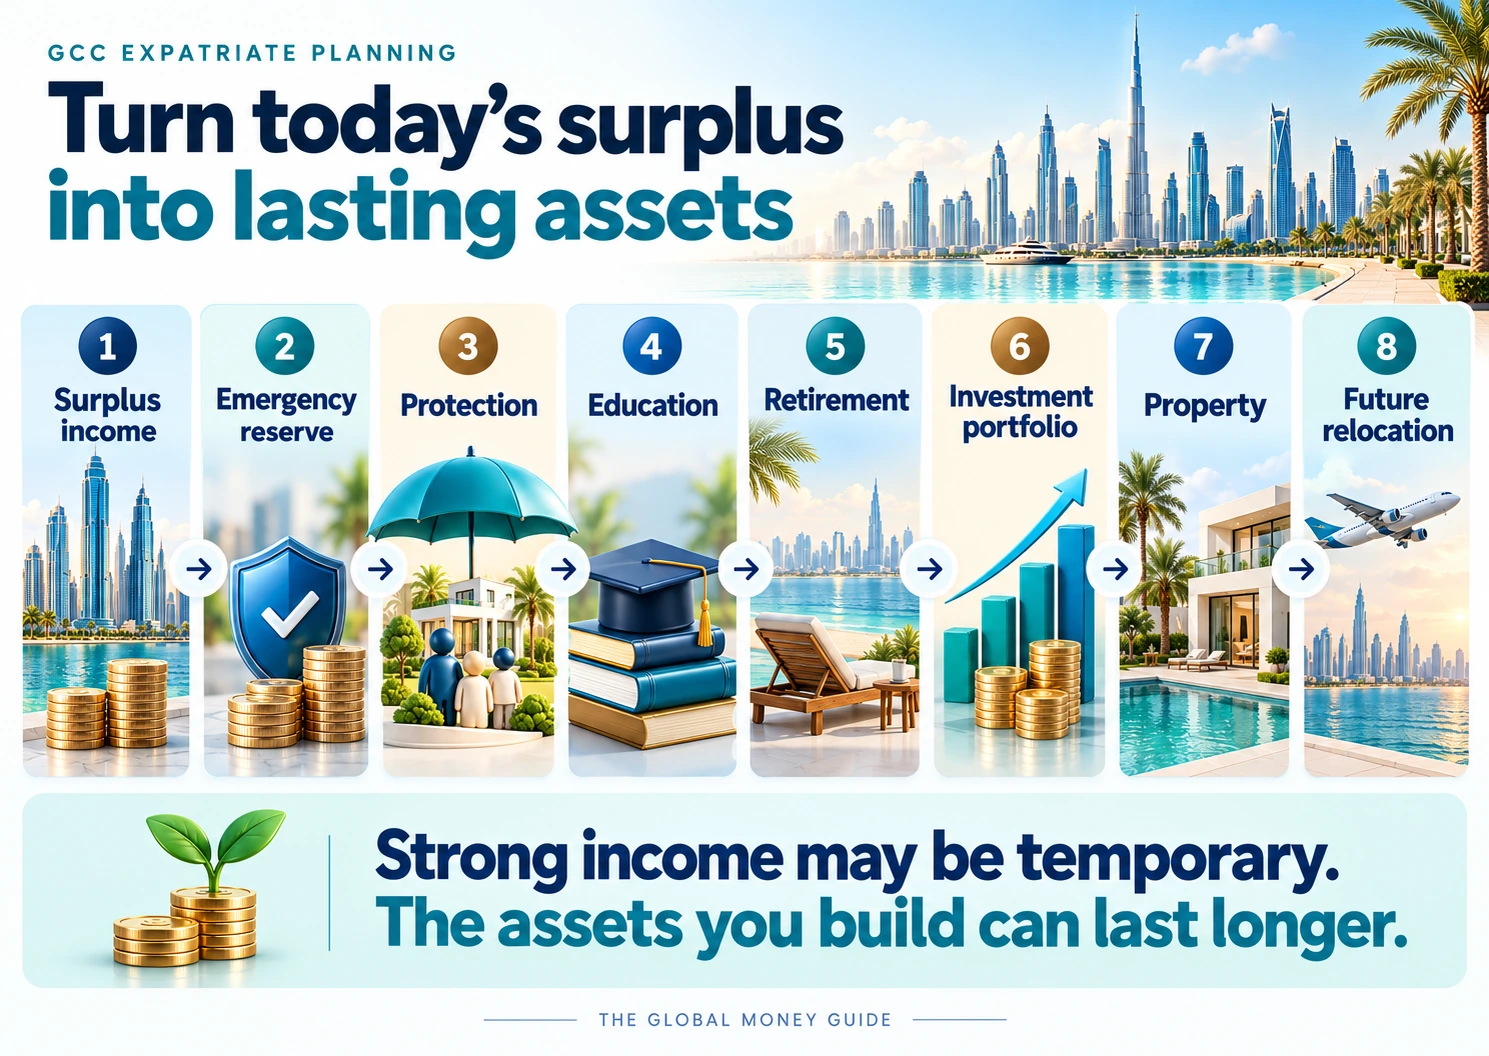
Turn today’s surplus into lasting assets
Strong income may be temporary. The assets you build can last longer.
What will the earning years create?
What do you want the years of surplus income to have created by the time you leave? Separate a relocation and emergency reserve from money for education, retirement and long-term investing.
Estimate your end-of-service benefit. Consider how a possible payment could support a move, a career break or your next goal once eligibility and timing are confirmed.
Follow the question that matters now.
Create a repeatable surplus
Allow for annual bills, family support and lifestyle before setting a sustainable contribution.
Keep the plan resilient
Review accessible reserves and cover that may change when employment or residence changes.
Preserve education choices
Compare future costs by destination and build a named family saving plan.
Fund the next chapter
Use a retirement budget and a destination range, including housing and healthcare.
Turn accumulated cash into a plan
Give property, business opportunities, longer-term investment and legacy separate jobs.
Connect your GCC years with your next destination
Keep a separate relocation reserve, choose a planning currency and make the exchange-rate assumption explicit. Current tools convert a whole illustration after your confirmation; they do not forecast different income and destination currencies independently.
Nationality alone does not determine tax or legal treatment. Residence, ownership and the countries involved matter. Jurisdiction-specific sources and dates are recorded in the linked guides.