
Retirement Planner
Start with the life you would like. Explore the savings that could support it.
Questions to put this goal in context
- What would you like retirement to look like?
- Do you expect housing costs to continue in retirement?
- Will you have other retirement income?
- Would you like to leave money behind?
For reflection only. You do not need to submit answers.
01Your retirement timeline
02The lifestyle you have in mind
Not sure what budget to use?
Explore retirement destinations03What you have and save
Retirement growth, other income and legacy
Use growth assumptions after estimated investment charges. Tax and investment volatility are not modelled.
Retire at 65 · 30 years until retirement · Plan until 95 $3,000 monthly budget today; $88,577 first-year spending
$1,829 / month
- Planned monthly saving
- $1,200
- Additional monthly saving
- $629
Your current plan projects to $1,169,416, leaving a $612,581 gap at retirement. The model estimates $1,829 a month, or $629 more than planned, to reach the target.
Illustrated retirement fund and withdrawals
The line shows the projected fund; bars show planned annual withdrawals from it. The retirement marker separates saving from drawdown. Values are in future money, with monthly withdrawals aggregated into annual bars.
| Measure | Your illustration | What it means |
|---|---|---|
| Retirement timing | Age 65 · 30 years away | When the retirement income period begins |
| Monthly lifestyle budget today | $3,000 | Your spending goal in today’s money |
| First-year retirement spending | $88,577 | First year’s spending after assumed inflation |
| Current retirement assets | $0 | Assets already set aside for retirement |
| Required retirement fund | $1,781,997 | Capital to support withdrawals and any legacy |
| Projected fund at retirement | $1,169,416 | Current assets and saving, with assumed growth |
| Capital shortfall at retirement | $612,581 | Difference between the required and projected fund |
| Planned monthly saving | $1,200 | What you currently intend to save |
| Estimated monthly saving needed | $1,829 | Illustrated level to meet the future payments |
| Additional monthly saving | $629 | Increase above your planned saving, if any |
A simple way to read your result
Begin with your lifestyle
$3,000 a month today, adjusted for inflation, sets the spending goal.
Allow for future income
The target fund allows for other income, withdrawals, growth and any legacy target.
Compare the current plan
$1,169,416 projected against $1,781,997 required; a $612,581 capital gap.
Explore what could change
Compare saving more, retiring later or adjusting your lifestyle budget.
What may change: investment returns and their timing, inflation, lifespan, other income, currency and tax.
View annual retirement withdrawals
| Age | Lifestyle | Other income | Fund withdrawal |
|---|---|---|---|
| 65 | $88,577 | $21,935 | $66,642 |
| 66 | $91,234 | $22,374 | $68,860 |
| 67 | $93,971 | $22,821 | $71,150 |
| 68 | $96,790 | $23,277 | $73,513 |
| 69 | $99,694 | $23,743 | $75,951 |
| 70 | $102,684 | $24,218 | $78,467 |
| 71 | $105,765 | $24,702 | $81,063 |
| 72 | $108,938 | $25,196 | $83,742 |
| 73 | $112,206 | $25,700 | $86,506 |
| 74 | $115,572 | $26,214 | $89,358 |
| 75 | $119,039 | $26,738 | $92,301 |
| 76 | $122,611 | $27,273 | $95,337 |
| 77 | $126,289 | $27,819 | $98,470 |
| 78 | $130,078 | $28,375 | $101,703 |
| 79 | $133,980 | $28,943 | $105,037 |
| 80 | $137,999 | $29,521 | $108,478 |
| 81 | $142,139 | $30,112 | $112,027 |
| 82 | $146,404 | $30,714 | $115,689 |
| 83 | $150,796 | $31,328 | $119,467 |
| 84 | $155,319 | $31,955 | $123,365 |
| 85 | $159,979 | $32,594 | $127,385 |
| 86 | $164,778 | $33,246 | $131,532 |
| 87 | $169,722 | $33,911 | $135,811 |
| 88 | $174,813 | $34,589 | $140,224 |
| 89 | $180,058 | $35,281 | $144,777 |
| 90 | $185,460 | $35,986 | $149,473 |
| 91 | $191,023 | $36,706 | $154,317 |
| 92 | $196,754 | $37,440 | $159,314 |
| 93 | $202,657 | $38,189 | $164,468 |
| 94 | $208,736 | $38,953 | $169,783 |
How this illustration works
Monthly saving is added at month end until retirement. Retirement spending is withdrawn at month start, then the remaining fund grows. Other income offsets spending. The target pot also allows for your terminal legacy. No guarantee, tax estimate or probability of success is implied.
For information and guidance only. Results are illustrative, based on your assumptions, and are not personalised financial advice. Assumed returns are not guaranteed; investments can fall as well as rise. Methodology & limitations
How the direction of funding changes
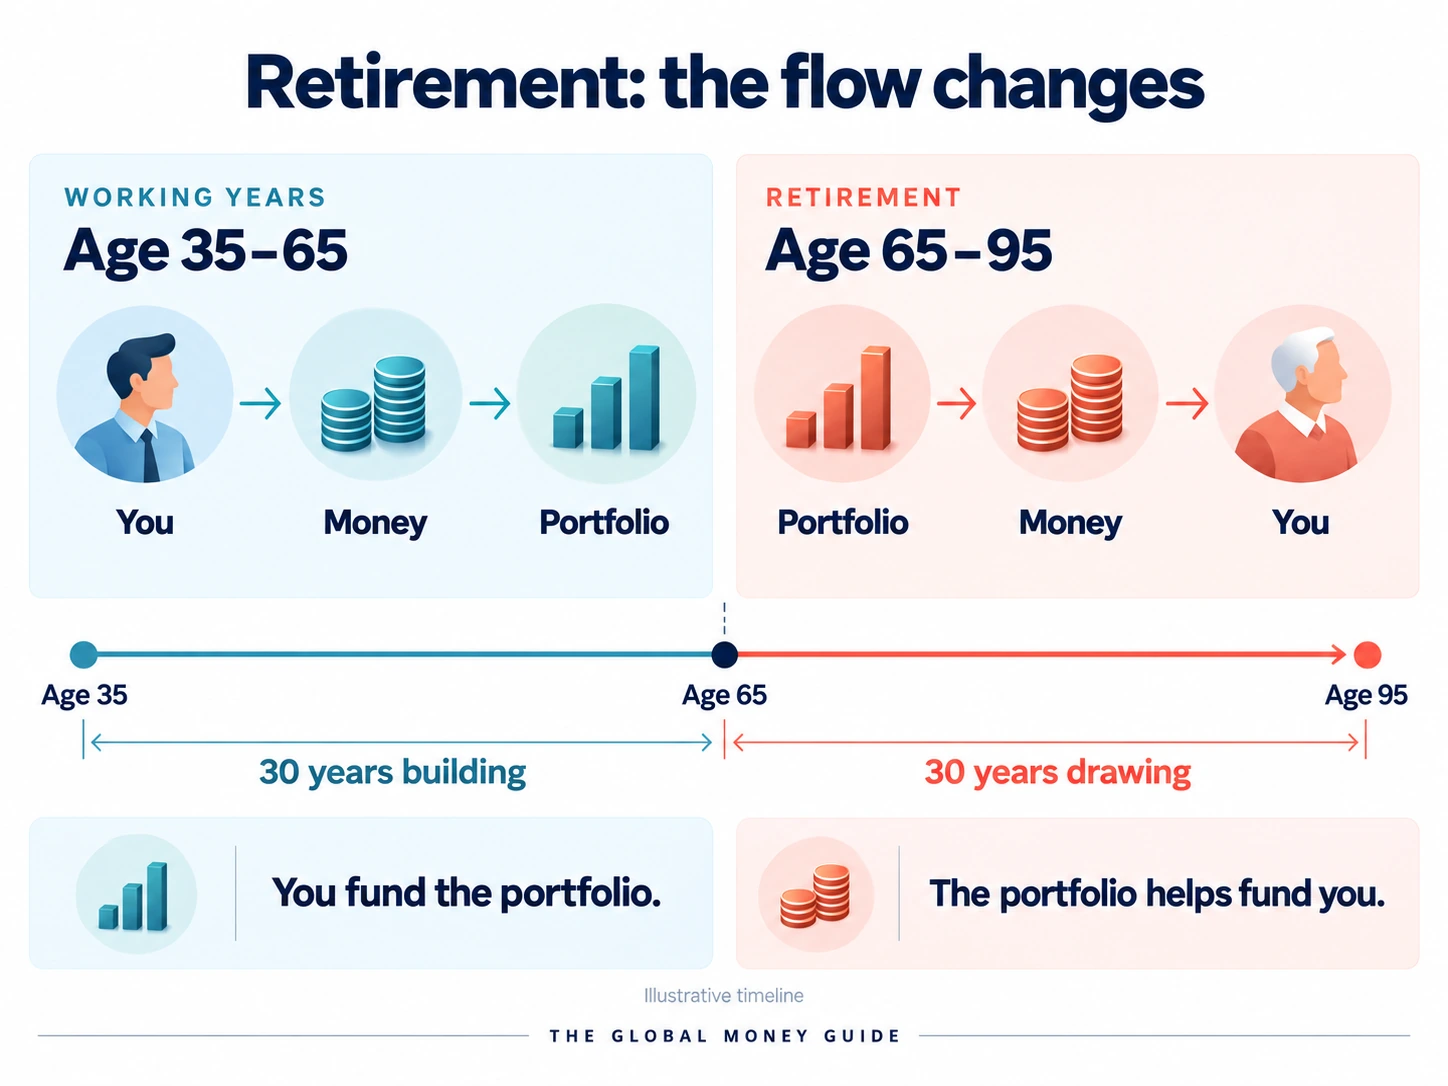
Retirement: the flow changes
Illustrative timeline
You contribute money to the portfolio.
The portfolio provides money to help fund you.
The illustration shows 30 years building, from age 35 to 65, followed by 30 years drawing, from age 65 to 95.
How much retirement income could your savings support?
Begin with a monthly budget in today’s money, then connect your retirement age, existing assets, future saving, other income and withdrawals. Plan for where you want to retire, not simply where you live today. The Retirement Destination Guide helps you build a starting budget.
A worked example with visible assumptions
At age 40, a $3,000 monthly lifestyle budget rises to $6,367 at age 65 with 3% annual inflation. Planning until 90, starting with $50,000, no other income or legacy, and assuming 6% growth before and 4% during retirement gives an illustrative monthly saving requirement of $2,160. Saving arrives at month end; withdrawals at month start. Returns are assumed after estimated charges; tax, volatility and sequence risk are not modelled.