
Updated 2026-09-27 · Global · General education
Retirement is not when the cost of living stops
It may be when your salary stops. The goal is an income that can support the life you want, alongside pensions or other resources. A large pot is useful only in relation to what it must fund.
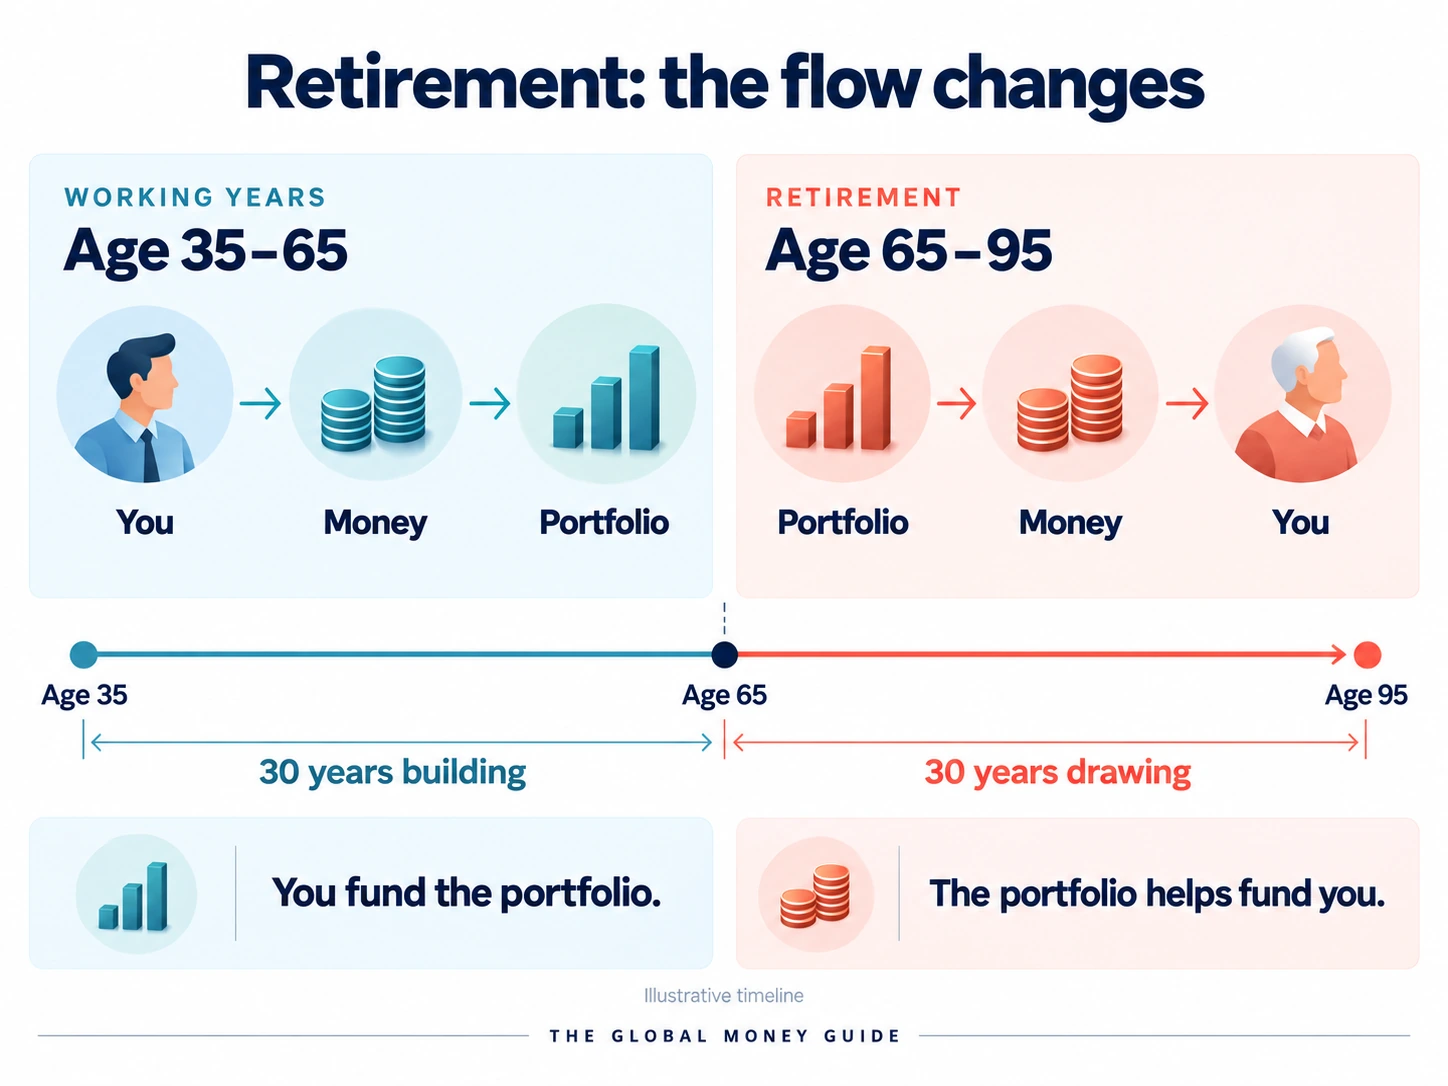
Retirement: the flow changes
Illustrative timeline
You contribute money to the portfolio.
The portfolio provides money to help fund you.
The illustration shows 30 years building, from age 35 to 65, followed by 30 years drawing, from age 65 to 95.
Give the lifestyle a monthly budget
Start with housing and bills, food, transport, travel and healthcare. Decide whether housing costs continue and where you might live. The Retirement Destination Guide provides a benchmark; Build My Budget lets you replace it with your own spending.
Today’s money and tomorrow’s spending
Connect the income need to a fund
The planner projects spending and other retirement income separately. It estimates the fund needed to pay the difference across the retirement period, plus any target legacy. Current assets and saving are then projected to retirement and compared with that requirement.
Retire later
More accumulation time and fewer withdrawal years can change the requirement materially. Test the lifestyle implications too.
Plan for a longer life
An extra five years may require more funding. “Plan until 95” is an assumption, not a prediction.
Change the spending or other income
A smaller gap between spending and income reduces the demand on the portfolio. Use realistic, consistent amounts.
I do not know where I will retire
Use scenarios. Compare two destinations, alternative housing assumptions and their currencies. Keep today’s money separate from future nominal amounts, and review healthcare, tax and access before making a move.

Build, test and keep a copy
Inside the planner, test another retirement age and download your one-page retirement illustration. You can discuss the assumptions with a planner when you want help applying them personally.
For information and guidance only. Results are illustrative, based on your assumptions, and are not personalised financial advice. Methodology & limitations